Most loan apps in the Philippines charge between 0.5% to 6% per month in interest, plus additional fees that can quietly push your total repayment much higher than you expected.
If you borrowed ₱5,000 and thought you’d pay back ₱5,300 — think again.
By the time processing fees, service charges, and late penalties are added, some borrowers end up repaying close to double the original amount, especially on short-term loans with 7 to 14-day terms.
This guide breaks down every cost you need to know before tapping “Apply Now.”
How Loan App Interest Rates Work In The Philippines
The nominal interest rate shown in most loan apps is usually a monthly figure, not annual.
That sounds small — until you convert it.
A 3% monthly rate equals roughly 36% annually.
Some apps advertise “low daily rates” like 0.1% per day, which translates to 3% monthly or 36.5% per annum.
The SEC (Securities and Exchange Commission) in the Philippines has set a cap of 6% per month on consumer lending interest rates for online lending platforms since Memorandum Circular No. 18 in 2019.
But many apps still find ways to push costs higher through fees that sit outside the interest rate label.
Effective Interest Rate vs. Nominal Rate
The nominal rate is what’s advertised.
The effective interest rate or EIR is what you actually pay when all costs are bundled in.
Here’s a simple example:
You borrow ₱3,000 for 30 days at 3% monthly interest.
Interest = ₱90.
But the app also deducts a ₱150 processing fee upfront, so you actually receive only ₱2,850 — while still repaying ₱3,090.
Your effective rate is no longer 3%.
It’s closer to 8.4% for that month alone.
This is one of the most common ways borrowers underestimate their actual borrowing cost.
Common Fees Charged By Loan Apps In Philippines
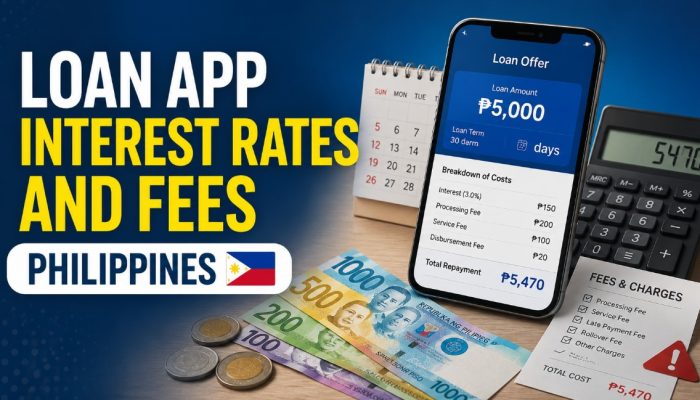
Beyond the interest rate, most online lending apps in the Philippines charge a combination of the following:
| Fee Type | Typical Range | Notes |
|---|---|---|
| Processing Fee | ₱50 – ₱500 | Often deducted upfront from loan amount |
| Service Charge | 1% – 5% of loan | Sometimes labeled as “platform fee” |
| Late Payment Penalty | 1% – 5% per day | Compounds quickly on missed due dates |
| Rollover / Renewal Fee | ₱100 – ₱300 | Charged when extending your loan term |
| Documentary Stamp Tax | ₱1.50 per ₱200 | Government-mandated, often passed to borrower |
| Disbursement Fee | ₱15 – ₱50 | GCash or bank transfer fees |
The late payment penalty is the most dangerous one.
One missed day at 2% penalty on a ₱5,000 loan adds ₱100 per day — that’s ₱3,000 in just one month on top of your original loan.
Loan App Interest Rate Comparison: Real Numbers
I’ve personally tested and reviewed several popular loan apps available to Filipino borrowers to track what they actually charge versus what they advertise.
Here’s a comparison based on a ₱5,000 loan with a 60-day term:
| Loan App | Monthly Interest | Processing Fee | Total Repayment (Est.) |
|---|---|---|---|
| Tala loan | 3% | ₱0 | ₱5,300 |
| Cashola | 5% | ₱250 | ₱5,750 |
| Funpera | 1.5% | ₱350 upfront | ₱5,500 |
| Bene | 2.5% | ₱100 | ₱5,350 |
Note: Estimates exclude late fees and assume on-time payment.
The takeaway: an app with a lower stated interest rate isn’t always the cheapest if upfront fees are high.
Always calculate the total cost of credit — not just the monthly rate.
You can check verified and SEC-registered loan apps at dienbiencflit before deciding which one fits your situation.
Why Short-Term Loan Fees Hit Harder
A 15-day loan sounds convenient.
But here’s what most borrowers don’t realize: fees like processing charges are a flat cost regardless of how long you borrow.
If you borrow ₱2,000 for 15 days with a ₱200 processing fee and 2% monthly interest, your fee alone represents a 10% cost on just that two-week term.
Annualized, that’s equivalent to over 260% APR.
This is why short-term micro-loans from loan apps often have a higher real cost than traditional bank loans — even if the nominal rate looks smaller.
What The SEC Rules Say About Loan Fees
The Securities and Exchange Commission Philippines has issued multiple circulars regulating online lending platforms.
Under SEC Memorandum Circular No. 18, Series of 2019:
- Interest rates are capped at 6% per month or 0.2% per day for short-term consumer loans.
Under SEC Memorandum Circular No. 10, Series of 2021:
- Total charges, fees, and penalties cannot exceed 100% of the original principal loan amount.
This 100% cap is critical.
It means even if you miss payments for months, the lender cannot legally collect more than double your original loan.
But some unregistered or fake loan apps ignore these rules entirely.
Understanding how to identify a fake loan app before applying can save you from illegal lenders who charge far beyond the SEC caps.
Case Study: Ate Linda’s Experience With A Short-Term Loan App
A friend I’ll call Ate Linda borrowed ₱4,000 from an online lending app in Quezon City.
The app showed “1.5% monthly interest.”
She assumed she’d pay back around ₱4,060.
What she didn’t see clearly: a ₱250 processing fee deducted at disbursement, a ₱50 GCash fee, and when she missed her due date by 5 days — a ₱200 late penalty.
Her actual repayment was ₱4,560 — more than 14% higher than she expected.
Her experience is not unusual.
It’s actually one of the most common complaints filed with the SEC and BSP about mobile lending apps.
Hidden Charges To Watch For
Some fees don’t appear in the main terms screen.
They’re buried in the fine print or only disclosed at disbursement.
For a deeper understanding of how these work, reading about hidden charges in loan apps can help you spot red flags before you sign anything.
Common hidden fees to look for:
Automatic Renewal Fee — Some apps auto-renew your loan if you don’t repay in full and charge a rollover fee without clear notification.
Insurance Premium — Some apps add a small credit life insurance deduction that you didn’t opt into consciously.
Data Access Fee — Framed as a “system requirement,” some apps charge for accessing your credit report or verifying your information.
Penalty for Early Repayment — A small number of apps penalize you for paying ahead of schedule.
How To Calculate Your Real Loan Cost
Before you apply, do this simple calculation:
Step 1: Get the total interest = Principal × Monthly Rate × Number of Months.
Step 2: Add all upfront fees (processing, service charge, disbursement fee).
Step 3: Add total = Interest + Fees.
Step 4: Divide total by the principal and multiply by 100 to get the real percentage cost.
Example: ₱5,000 loan, 3% monthly for 1 month, ₱200 processing fee.
Interest = ₱150.
Total cost = ₱350.
Real cost percentage = (₱350 ÷ ₱5,000) × 100 = 7%.
That 7% for one month equals 84% annualized.
Choosing A Loan App That Gives You Fair Rates
Not all loan apps are predatory.
Some SEC-registered digital lenders offer transparent pricing, reasonable annualized percentage rates, and no hidden charges.
When comparing apps, look for:
- Clear disclosure of the Annual Percentage Rate (APR) or Effective Interest Rate (EIR).
- SEC registration number visible in the app or website.
- No upfront fee deducted from the loan principal before disbursement.
- A clear breakdown of all charges before you confirm the loan.
- A repayment schedule that shows exactly how much you owe each period.
If you want to make a smarter choice, reading a guide on how to choose a safe loan app in the Philippines walks you through the exact criteria to filter out risky lenders.
Frequently Asked Questions
What is the maximum interest rate a loan app can charge in the Philippines?
The SEC caps interest at 6% per month or 0.2% per day for short-term consumer loans.
Total charges including fees and penalties cannot exceed 100% of the original loan principal under SEC Memorandum Circular No. 10, 2026.
Do all loan apps in the Philippines charge a processing fee?
Not all, but most do.
Processing fees typically range from ₱50 to ₱500, and are often deducted from your loan before disbursement, meaning you receive less than what you applied for.
Is a low monthly interest rate always better?
Not necessarily.
A low monthly rate paired with high upfront fees can result in a higher real cost than an app with a slightly higher rate but zero processing fees.
Always compare the total repayment amount, not just the stated rate.
What happens if I miss a payment on a loan app?
Most apps charge a daily penalty between 1% and 5% of the outstanding balance.
Under SEC rules, total penalties and fees across the life of the loan cannot exceed 100% of your original principal.
Are loan app fees negotiable?
Generally, no.
Loan apps use automated systems and set fee structures that don’t accommodate individual negotiation.
Your best option is to compare apps before applying and choose one with fees you can comfortably absorb.

Để lại một bình luận